US Equity Portfolio
Rendimientos mensuales
Rendimiento de la estrategia por mes natural con alpha.
Crecimiento desde el inicio
Valor de un índice base 100 invertido al inicio de la estrategia, comparado contra el índice de referencia seleccionado. Rendimientos netos, expresados en la divisa seleccionada.
Alpha acumulado
Exceso de rendimiento acumulado de la estrategia sobre el índice de referencia.
Métricas de rendimiento
Métricas calculadas sobre la historia disponible de la estrategia. Las ventanas móviles de 1 año utilizan el periodo completo cuando existe menos de un año de historia.
Riesgo y eficiencia
Volatilidad anualizada móvil de 1 año de la estrategia frente al índice de referencia, error de seguimiento móvil de 1 año, y caída (drawdown) desde máximos de la estrategia y del índice.
Resumen de posiciones
Posiciones actuales de la estrategia y su distribución por industria.
Distribución por industria de los ETFs
Composición por industria de los ETFs de referencia, para contrastar con la distribución de la estrategia.
eToro
A part of my personal wealth is invested through eToro, where every position and every result is recorded by the broker itself. That makes this track record externally verifiable rather than self-reported.
Monthly returns
Strategy return by calendar month with alpha.
Growth since inception
Value of a base-100 index invested at the strategy's inception.
Cumulative alpha
Cumulative excess return over the benchmark.
Performance metrics
Metrics computed over the available history.
Risk and efficiency
Rolling volatility, tracking error, drawdown and information ratio.
Follow and verify
Open my public eToro profile to see the portfolio and its results as the broker reports them. The invite link is for anyone who wants to open their own eToro account.
eToro is a multi-asset platform. Investing carries risk.
About me
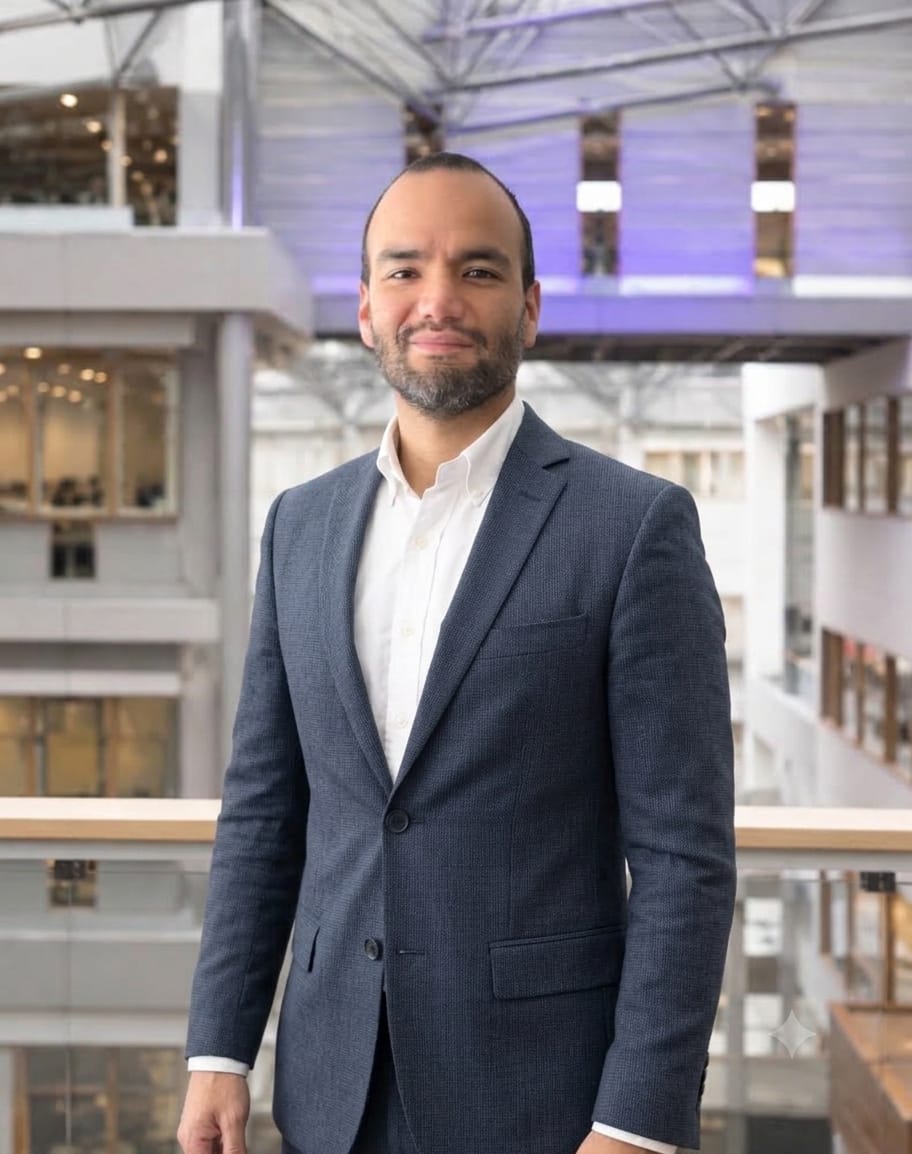
I'm Juan Carlos Barradas — an equity portfolio manager with over 10 years of experience spanning quantitative modeling, derivatives, and multi-asset management.
I pair rigorous quantitative research with disciplined fundamental judgment. I hold an MSc in Quantitative Finance from BI Norwegian Business School (International Scholarship) and a BSc in Actuarial Science; I passed the three CFA exams, the first SOA exams, and I build my own factor models, backtesting frameworks, and portfolio analytics in Python.
In my professional career I monitored market risk, traded derivatives, and managed investment funds at firms including HSBC, Actinver, and Scotiabank, giving me a hands-on feel for markets well beyond the models.
Investment Strategy

This is a personal investment strategy funded entirely with my own wealth. My incentives are therefore fully aligned with the results: every position reflects genuine conviction and real skin in the game.
The strategy focuses on the US equity market, the deepest and most liquid opportunity set in the world. Security selection is driven by fundamental and quantitative models built entirely in-house — factor signals, valuation and quality screens, and systematic risk controls — pairing the discipline of a systematic process with the judgment of fundamental analysis.
Execution runs through some of the best international brokers, giving the portfolio institutional-grade access, pricing, and reliability. The result is a concentrated, actively managed book designed to compound capital while beating the major US indices.
Live results are in the Performance section.
Los rendimientos pasados no garantizan resultados futuros. La información mostrada es de carácter informativo, proviene de registros internos auditados de la estrategia y no constituye una oferta ni recomendación de inversión. Toda la información proporcionada tiene únicamente fines educativos e informativos y no constituye asesoría de inversión, financiera ni legal.